Is working capital a loan?
Working capital describes a business need, not one universal loan product. Depending on the provider and business profile, it may be financed through a line of credit, term financing, or another commercial structure.
Contractors often pay for materials, payroll, and project costs before customer payments arrive. Working capital may help bridge that timing gap and keep active jobs moving.
Contractor Capital helps contractors explore working capital options through independent financing providers.
Payroll & labor • Materials & supplies • Project costs • Cash flow gaps
Working capital supports daily operations and active projects. For contractors, that can mean paying crews and suppliers, buying materials, or covering fuel, mobilization, insurance, and job startup costs before the related customer payment arrives.
It describes the financing need, not one universal product. The structure a provider may offer depends on the business profile, cash flow, intended use, and provider requirements.
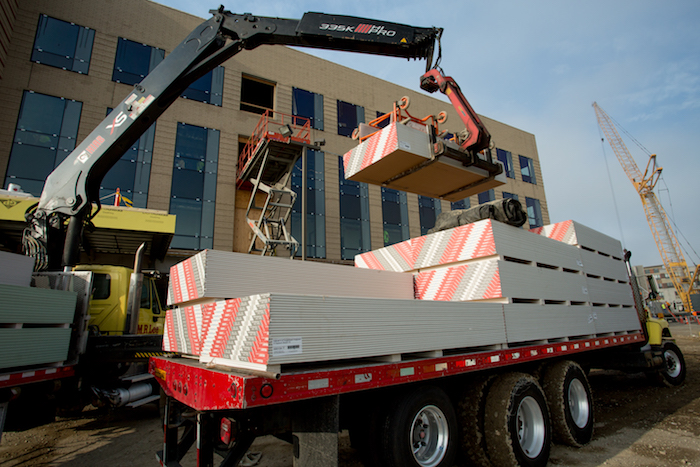
Project costs begin before the related customer or project payment arrives.
Cash goes out
Costs continue
Cash flow timing gap
Cash comes in
Purchase job materials before the next draw or customer payment.
Support field crews, office staff, and subcontractors while work is underway.
Cover mobilization and other costs that arrive before collections begin.
Manage periods when several jobs require spending at the same time.
Address fuel, insurance, rent, software, or permits where appropriate.
Prepare for predictable work that requires spending before related revenue arrives.
Working capital may be worth exploring when expected collections and current job costs do not align.
Working capital is generally better suited to a defined operating or timing need than to permanently covering recurring losses or chronic cash flow deficits.
A more specific purpose may be worth reviewing on its own terms.
A truck, machine, or other equipment
Equipment FinancingEligible unpaid commercial invoices
Invoice FinancingReusable access to capital
Business Line of CreditA qualifying investment with a longer horizon
SBA / Term FinancingShorter duration capital supported by revenue
Revenue-Based FundingThe same operating need may be addressed through different financing arrangements. Available structures depend on the business and the independent provider.
May provide reusable access to capital, subject to the provider agreement.
Provides a defined amount repaid under the agreed provider terms.
May fit when eligible unpaid commercial invoices drive the timing need.
May suit some businesses, with cost and repayment characteristics that can differ from traditional financing.
May be worth considering for qualifying needs with a longer horizon.
Depending on the financing structure and provider, factors may include:
Monthly revenue, time in business, bank activity, and deposit consistency.
Cash flow, average balances, credit profile, and existing obligations.
Requested amount, intended use of funds, and supporting documentation.
Tell us about your business, funding need, and intended use of funds. Contractor Capital can help identify potential options through independent financing providers.
Working capital describes a business need, not one universal loan product. Depending on the provider and business profile, it may be financed through a line of credit, term financing, or another commercial structure.
Potential uses may include materials, payroll, subcontractors, mobilization, and other operating costs. Eligibility and permitted uses depend on the financing provider and structure.
Working capital is the reason a business needs funds; a line of credit is one possible financing structure. A provider may offer reusable access to capital under an agreement, while other structures provide a defined amount for a particular need.
Depending on the provider and structure, review may include revenue, business bank activity, operating history, credit profile, existing obligations, requested amount, use of funds, and supporting documents. There is no universal checklist.
Tell us where the funding need shows up in your business and how you plan to use the capital. Contractor Capital can help review options through independent financing providers.
Explore reusable capital for recurring project expenses.
Review options tied to a truck, machine, or productive asset.
Consider eligible commercial receivables as the funding basis.
Compare a defined amount with reusable access to capital.
Understand the cash flow details a provider may review.
Contractor Capital is not a lender and does not provide financial, legal, or tax advice. Funding availability, terms, rates, and approvals depend on the applicant, lender, business profile, creditworthiness, documentation, revenue, and other underwriting factors. Information on this page is educational and should not be considered a guarantee of approval or specific funding terms.